SEC-registered investment advisorMRA Advisory Group
In-house tax preparationMRA Tax Services
Brazil-based specialist attorneyBrazilian tax and residency
English and PortugueseOne team, both languages
Why It Matters
There is no US–Brazil income tax treaty.
Without a treaty, each country applies its own rules to the same income. Reporting gaps on either side tend to grow quietly over time.
Coordinating both sides early is usually simpler than fixing them later.
Gaps we often see
An unfiled Brazilian exit. Brazil may still treat you as a resident years after you moved.
An undeclared US account. Foreign account reporting applies on both sides.
A Brazilian fund the IRS treats as a PFIC. Common local investments can carry special US reporting.
Who We Help
Three situations, one coordinated approach.
Americans living in Brazil
You file US returns on worldwide income and may also be a Brazilian tax resident filing IRPF.
You may need us if
You have become a Brazilian tax resident and still file Form 1040
You want your US and Brazilian returns to tell the same story
You hold Brazilian accounts or funds that must be reported to the IRS
Brazilians living in the US
Many never formally exited the Brazilian tax system, so Brazil may still treat them as residents.
You may need us if
You moved without filing a formal tax exit from Brazil
You still own property, accounts, or a company in Brazil
You are not sure which country considers you a tax resident
Families and investors in both
Dual-tax-resident households with assets on both sides: US brokerage, Brazilian funds, real estate, offshore companies.
You may need us if
You hold a US brokerage account alongside Brazilian funds or property
You own an offshore company or are weighing a holding structure
Members of your family file in different countries
Services
Both sides of your tax life, handled together.
01
US tax for Americans abroad
Form 1040 on worldwide income
Foreign Earned Income Exclusion and Foreign Tax Credit analysis
FBAR (FinCEN 114) and Form 8938 reporting
PFIC reporting for non-US funds
Catch-up filings, including the IRS Streamlined procedures when eligible
02
Brazil tax compliance and regularization
Annual Brazilian income tax return (IRPF)
Formal tax exit from Brazil (Comunicação e Declaração de Saída Definitiva)
Amended or late returns
Reporting of foreign assets and income under Law 14,754/2023
Central Bank foreign capital reporting (CBE), when applicable
03
Cross-border tax advisory
Tax residency analysis
Selling Brazilian property while living abroad
Moving money between countries
Holding structures and investment accounts, reviewed from both tax systems
Questions We Help Answer
Start with the question you already have.
01
I moved to the US years ago. Am I still a tax resident in Brazil?
02
I live in Brazil. Do I still need to file in the US, and how do I avoid paying tax twice?
03
I sold (or plan to sell) property in Brazil. What is owed, and where?
04
My Brazilian investment fund appears on my US return. What is a PFIC?
05
I never reported my foreign accounts. What are my options now?
06
I am planning to move between the two countries. What should I do before I go?
Examples
One income. Two countries.
The same asset can look very different to each tax system. A few common situations, and how each country may look at them.
Looking at Brazil from the US
How the US may treat Brazilian income and companies
Brazilian investment funds+
A Brazilian company you control+
Brazilian bank and brokerage accounts+
Selling property in Brazil+
Brazilian private pension (PGBL, VGBL)+
Looking at the US from Brazil
How Brazil may treat US income and accounts
If you never formally left Brazil+
A US brokerage account+
A US LLC or company+
US salary+
401(k), IRA, and US retirement accounts+
Why coordination matters
With no income tax treaty, each country applies its own rules. Looking at both sides together helps the two returns tell the same story.
Important: These examples are educational only and are not tax or legal advice. They describe how each country may look at an item, not how it will apply to you. Treatment depends on your individual circumstances, and rules in both countries may change. Speak with a qualified professional before acting.
How It Works
How regularization works
01
Diagnostic
Review residency status, past filings, and assets on both sides.
02
Mapping
Identify gaps, deadlines, and exposure in each country.
03
Regularization
Prepare and file what is missing or needs correction, in the right order.
04
Ongoing compliance
Annual filings on both sides, coordinated with your financial plan.
Ways to Work With Us
Clear scope, from the first step.
Recommended first step
Cross-Border Diagnostic
Pricing shared during your diagnostic call
Residency review in both countries
Review of past filings and reported assets
Written summary of gaps and recommended next steps
US, Brazil, or both
Annual Compliance
Pricing shared during your diagnostic call
US federal return and international information forms
Brazilian IRPF and foreign asset reporting
Both sides prepared on one coordinated calendar
Catch-up and corrections
Regularization Project
Quoted after diagnostic
Scope defined by your diagnostic
Missing or amended filings, in the right order
Coordinated across both countries
Final scope and fees are confirmed in a written engagement.
Meet the Specialist
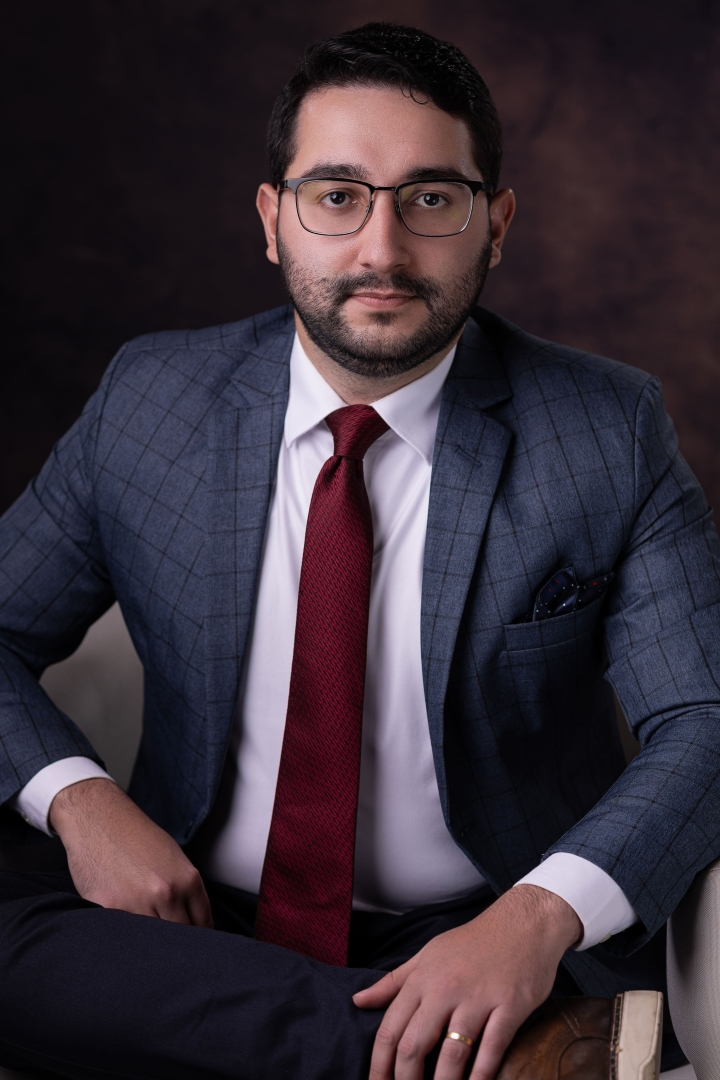
Rodrigo Brito
Attorney in Brazil and International Tax Advisor, MRA International Advisory
Rodrigo is a Brazilian attorney (OAB/BA 70.757) who works with Brazilians living abroad and families with assets in both countries. His focus is the point where tax residency, investments, and succession meet.
His career spans the investment market, corporate law, and international tax planning. That path gives him a connected view of investments, estate planning, and tax across Brazil and the US. It helps clients see how a decision on one side affects the other before they make it.
500+Brazilians advised abroad
32Countries of residence
EN · PTLanguages
Focus Areas
Brazilian tax residency and formal exit
Foreign assets under Law 14,754/2023
Brazilian and US investments, viewed from both tax systems
International holding structures and succession
Experience
Cross-border tax and wealth planning for Brazilians abroad
Corporate attorney, BRC Advocacia (2021–2025)
Investment advisor, Inovatti Investimentos, XP Inc. accredited office (2019–2021)
Education
LL.M., Law Practice and Tax Reform, Faculdade Santo Ivo
Wealth Management, PUCRS
LL.B., FASB
Connected to the Rest of Your Plan
One decision can affect the rest.
Where you are a tax resident shapes how you invest, how you plan, and how your estate passes on. We look at them together.
Often yes. It depends on your citizenship, where you are a tax resident, and where your income and assets are.
What does a formal exit from Brazil involve?+
Formally exiting the Brazilian tax system typically involves filing a Comunicação e Declaração de Saída Definitiva (final exit declaration) confirming that you are no longer a Brazilian tax resident.
Can I catch up on years I did not file?+
In many cases, yes. MRA can help prepare catch-up or amended filings on both sides, including the IRS Streamlined Filing Compliance Procedures when you are eligible on the US side.
Who prepares my US return?+
US tax preparation is provided by MRA Tax Services, LLC.
Who handles the Brazilian side?+
Brazilian tax services are provided through MRA's independent contractor in Brazil, a Brazil-based specialist attorney.
Are legal services included?+
Brazilian legal services, when needed, are engaged separately and directly with the attorney. They are not provided by MRA Advisory Group or its affiliates.
What should I bring to the first consultation?+
Your advisor will let you know what to gather for your situation when you schedule your diagnostic call.
Start with the question in front of you.
A first conversation to understand your situation in both countries.
The content on this page is for educational purposes only and is not tax, legal, or investment advice. It does not guarantee any tax outcome, savings, or relief from penalties. There is currently no comprehensive income tax treaty between the United States and Brazil.
US tax preparation is provided by MRA Tax Services, LLC. Brazilian tax services are provided through MRA’s independent contractor in Brazil. Brazilian legal services, when needed, are engaged separately and directly with the attorney and are not provided by MRA Advisory Group or its affiliates.
MRA Advisory Group is a Registered Investment Advisor. Review MRA’s Form ADV Brochure ↗, Form CRS, and Privacy Policy for additional information. This material is subject to compliance review before publication.
Client Referral Disclosure
MRA Advisory Group (“MRA”) may recommend Nodawa Global Partners (“Nodawa”), an unaffiliated third-party tax firm, to clients seeking tax services in Brazil. If you engage Nodawa following a referral from MRA, MRA will receive compensation from Nodawa equal to 10% of the fees you pay Nodawa for tax services. Nodawa pays this compensation from the fees it collects; it is not an additional charge to you.
This arrangement creates a conflict of interest because MRA has a financial incentive to recommend Nodawa over other available providers. MRA considers your needs and circumstances when determining whether a referral is in your best interest.
You are not required to use Nodawa and remain free to select another tax professional. Your decision will not affect your access to MRA’s advisory services or the terms of those services.
If you choose Nodawa, you will enter into a separate engagement directly with Nodawa. Nodawa is responsible for its tax services, advice, and fees.